Quick answer: Yes, David Mount helps buyers in Northern Virginia purchase homes by assuming a seller’s existing low-interest-rate loan, including VA and FHA loans. When today’s mortgage rates are high, taking over a seller’s older, lower-rate loan can save a buyer hundreds of dollars a month. David has closed real assumable-loan purchases, including a military veteran who assumed a low-rate loan in 2024, and as a Veterans United preferred agent (top 10% nationally) he knows how to find these opportunities and guide buyers through them. Call or text David at 571-946-8418 or email david.mount@thereduxgroup.com.
What is an assumable loan, and why it matters now
An assumable loan lets a qualified buyer take over a seller’s existing mortgage, its balance, its monthly payment, and most importantly its interest rate, instead of taking out a brand-new loan at today’s higher rates. VA and FHA loans are generally assumable; most conventional loans are not. If a seller bought or refinanced during the low-rate years, that older loan can be worth more than any upgrade in the house, and a buyer who assumes it can lock in a payment that simply isn’t available on a new mortgage today.
The trade-offs are real, too: the buyer typically has to cover the gap between the purchase price and the remaining loan balance (in cash or with a second loan), and the lender must approve the buyer. With VA loans there are added details, such as how the seller’s VA entitlement is handled, worth understanding before you commit. David helps you weigh all of it clearly and connects you with lenders who actually process assumptions. Every loan and lender is different, so the specifics are always confirmed with a qualified lender.
David has actually done this, not just talked about it
Plenty of agents can define an assumable loan. Far fewer have closed one. David has, more than once:
- A military veteran who assumed a low-interest-rate loan (2024). David guided a veteran buyer through assuming a seller’s below-market loan, locking in a monthly payment well under what a new mortgage would have cost.
- An assumable-loan win against multiple offers (Alexandria, 2024). David helped buyer Andy A. build an offer around assuming the seller’s existing low-rate financing, and win in a competitive, multiple-offer situation.
How Andy assumed the seller’s VA loan and still won against multiple offers (Alexandria, 2024)
The situation. Andy, an active-duty first-time buyer, was not looking for just any home. He was looking only for homes with an assumable VA loan, which meant restricting the search to a small slice of the market: listings where the seller’s existing financing could be taken over. Those are rare, and when one appears, other buyers notice too. The home he wanted in Alexandria carried a VA loan at a rate under 3 percent. Assuming it would mean a monthly payment far below a new mortgage on the same house. Within a week of the listing going live, there were multiple offers.
What we did. A loan assumption takes longer to close than a conventional purchase, which normally makes it the weakest offer on the table. So we built the offer around the assumption instead of hiding it. Andy’s eligibility and the servicer’s requirements were lined up before we wrote the offer, so the listing agent could see a buyer who had already done the hard part. We paired that with terms that gave the sellers certainty on everything else, so the longer timeline was the only trade-off they were taking on.
The outcome. The sellers chose Andy’s offer. He closed in 2024 with the seller’s below-market VA loan in place, and his review afterward praised the way each stage was explained so he “felt informed and empowered throughout.”
Why it matters. An assumable loan can save a buyer more than any price negotiation, but only if the agent knows two things: how to find the few listings that qualify, and how to make an assumption offer competitive when other buyers show up. Most agents have never done either. This is one I have closed.
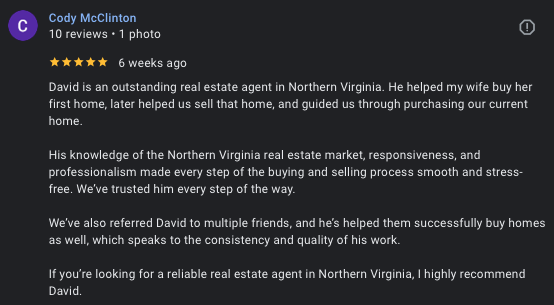
“David is an outstanding real estate agent in Northern Virginia. He helped my wife buy her first home, later helped us sell that home, and guided us through purchasing our current home… If you’re looking for a reliable real estate agent in Northern Virginia, I highly recommend David.”
Cody M. · repeat client, military veteran family (2024)
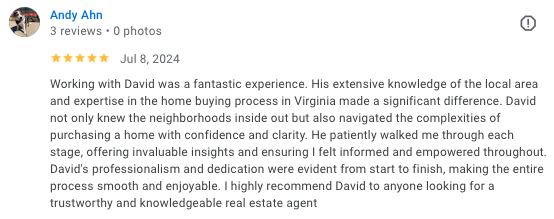
“Working with David was a fantastic experience. His extensive knowledge of the local area and expertise in the home buying process in Virginia made a significant difference… I felt informed and empowered throughout.”
Andy A. · home buyer, Alexandria (2024)
How Cody and his wife assumed a low-rate mortgage in Warrenton
Cody, a military veteran, and his wife are repeat clients: I helped her buy her first home, later sold that home for them, and in 2024 guided them into their current home in Warrenton (Fauquier County). That purchase was a loan assumption. Instead of taking out a new mortgage at 2024 rates, they assumed the seller’s existing low-interest-rate loan, which locked in a monthly payment that no new loan could match. The work on my side was the same as with Andy: identify the assumable opportunity, confirm the servicer’s process and timeline up front, and structure the offer so the seller was comfortable with the longer assumption closing. In Cody’s words, “His knowledge of the Northern Virginia real estate market, responsiveness, and professionalism made every step of the buying and selling process smooth and stress-free.”
Who an assumable loan is right for
Assuming a low-rate loan tends to be a great fit for veterans and VA buyers, buyers who are rate-sensitive and want a lower monthly payment, and buyers who have enough cash (or a second loan) to cover the gap between price and the existing balance. David works with buyers across Alexandria, Arlington, Fairfax City, Fairfax County, Falls Church, Loudoun County, and Prince William County, with a focus on single-family homes and townhomes. Learn more about how David helps military and PCS buyers and first-time buyers across Northern Virginia.
Want to buy with an assumable, below-market-rate loan? Tell David what you’re looking for, he’ll reply personally.
Frequently Asked Questions About Assumable Loans in Northern Virginia
Which loans are assumable?
VA and FHA loans are generally assumable by a qualified buyer; most conventional loans are not. The seller’s lender (the loan servicer) reviews and approves the assumption.
Do I have to be a veteran to assume a VA loan?
No, a non-veteran can assume a VA loan if they qualify. However, the seller’s VA entitlement generally stays tied to that loan until it is paid off, which can limit the seller’s ability to use VA financing again. A qualifying veteran buyer can sometimes substitute their own entitlement. David and a VA-savvy lender help both sides understand this before you proceed.
How do I find homes with assumable loans in Northern Virginia?
Assumable opportunities are not always advertised. David identifies them by reviewing financing details, asking the right questions of listing agents, and tapping his network, then helps you structure an offer that wins. He has done exactly this for buyers in 2024.
What is the catch with assuming a loan?
The main one is the equity gap: you usually need to cover the difference between the purchase price and the remaining loan balance, plus closing costs. Approval and processing also take coordination with the servicer. David helps you plan for both so there are no surprises.
Can an offer that assumes the seller’s loan win against other offers?
Yes, if it is prepared correctly. In 2024 David helped Andy, an active-duty first-time buyer searching only for VA-assumable homes, win an Alexandria home that drew multiple offers within a week of listing. The buyer’s eligibility and the servicer’s requirements were lined up before the offer was written, and the remaining terms gave the sellers certainty, so the longer assumption timeline was the only trade-off. Andy closed with the seller’s under-3-percent VA loan in place.
Talk to David about an assumable-loan purchase
If you want to buy in Northern Virginia and keep your monthly payment low, an assumable loan may be one of the smartest moves available right now. David Mount, REALTOR® with The Redux Group of eXp Realty and a Veterans United preferred agent, has closed these deals and can help you do the same. Call or text 571-946-8418 or email david.mount@thereduxgroup.com.