Quick answer: Yes, a pastor’s housing allowance counts as qualifying income for a mortgage. Fannie Mae requires a 12-month history, verification from the church (Form 1005 or a pay stub and W-2), and then adds the full allowance to monthly income; it does not have to be proven to continue. Because the allowance is excluded from federal income tax, many lenders also gross it up 15 to 25 percent, the same way they treat other nontaxable income. That turns a modest ministry salary into real purchasing power in Fairfax, Prince William, and Loudoun. I’m David Mount, a REALTOR with The Redux Group of eXp Realty and a man of faith. I have helped a pastor and his wife buy their first home in Kingstowne with room for the family they were raising, and church staff and families from several Northern Virginia congregations since. Call or text me at 571-946-8418 and tell me your church and your allowance; I will tell you what it buys.
Last reviewed and updated: October 22, 2026
How the housing allowance works on a mortgage application
- What it is: the portion of a minister’s compensation the church designates in advance for housing (IRC § 107). It is excluded from federal income tax up to the lesser of the designated amount, actual housing costs, or fair rental value plus utilities. It is still subject to self-employment tax.
- What the lender needs: a completed Request for Verification of Employment (Form 1005) from the church or your most recent pay stub and W-2, a 12-month history of receiving the allowance, and the church board’s resolution designating it. The full amount is added to your monthly qualifying income.
- Grossing up: because the allowance is nontaxable for income tax, most lenders will gross it up (count $1.15 to $1.25 for each $1.00) under their nontaxable income rules. Not every loan officer knows this; I work with ones who do.
- The IRS side: you still get the mortgage interest and property tax deductions on top of the allowance exclusion. Talk to a CPA who handles clergy; they are worth the fee.
Leaving the parsonage: what changes
A church that owns a parsonage and a pastor who owns nothing is a common Northern Virginia arrangement, and it leaves the pastor with no equity at retirement. The move to ownership usually happens when the church converts the parsonage benefit into a cash housing allowance. If that is your situation, three things to settle with your board first: the allowance amount (set it high; unused allowance is simply taxed), whether the church will help with a down payment (a gift or a loan, each with different tax treatment), and the timeline, since you will want to close before the parsonage is sold or reassigned.
Where church families buy
Most pastors want to live inside the congregation’s footprint but outside the price of the immediate neighborhood, and that is a solvable problem here. Kingstowne and Franconia for Alexandria and Springfield churches; Burke and Fairfax Station for the Braddock Road corridor; Centreville and Chantilly for western Fairfax congregations; Ashburn and Leesburg for Loudoun; Woodbridge, Dale City, and Bristow for Prince William. I know which townhouse communities in each of those have the extra bedroom a growing family needs at a price a ministry salary can carry.
Pastor or ministry staff member buying in Northern Virginia?
Call or text me at 571-946-8418. Tell me your church, your allowance, and how many bedrooms you need, and I will tell you what is realistic.
12+ years, $130M+ sold, 100+ five-star reviews. Serving church families across Northern Virginia.
A pastor’s family and their first home
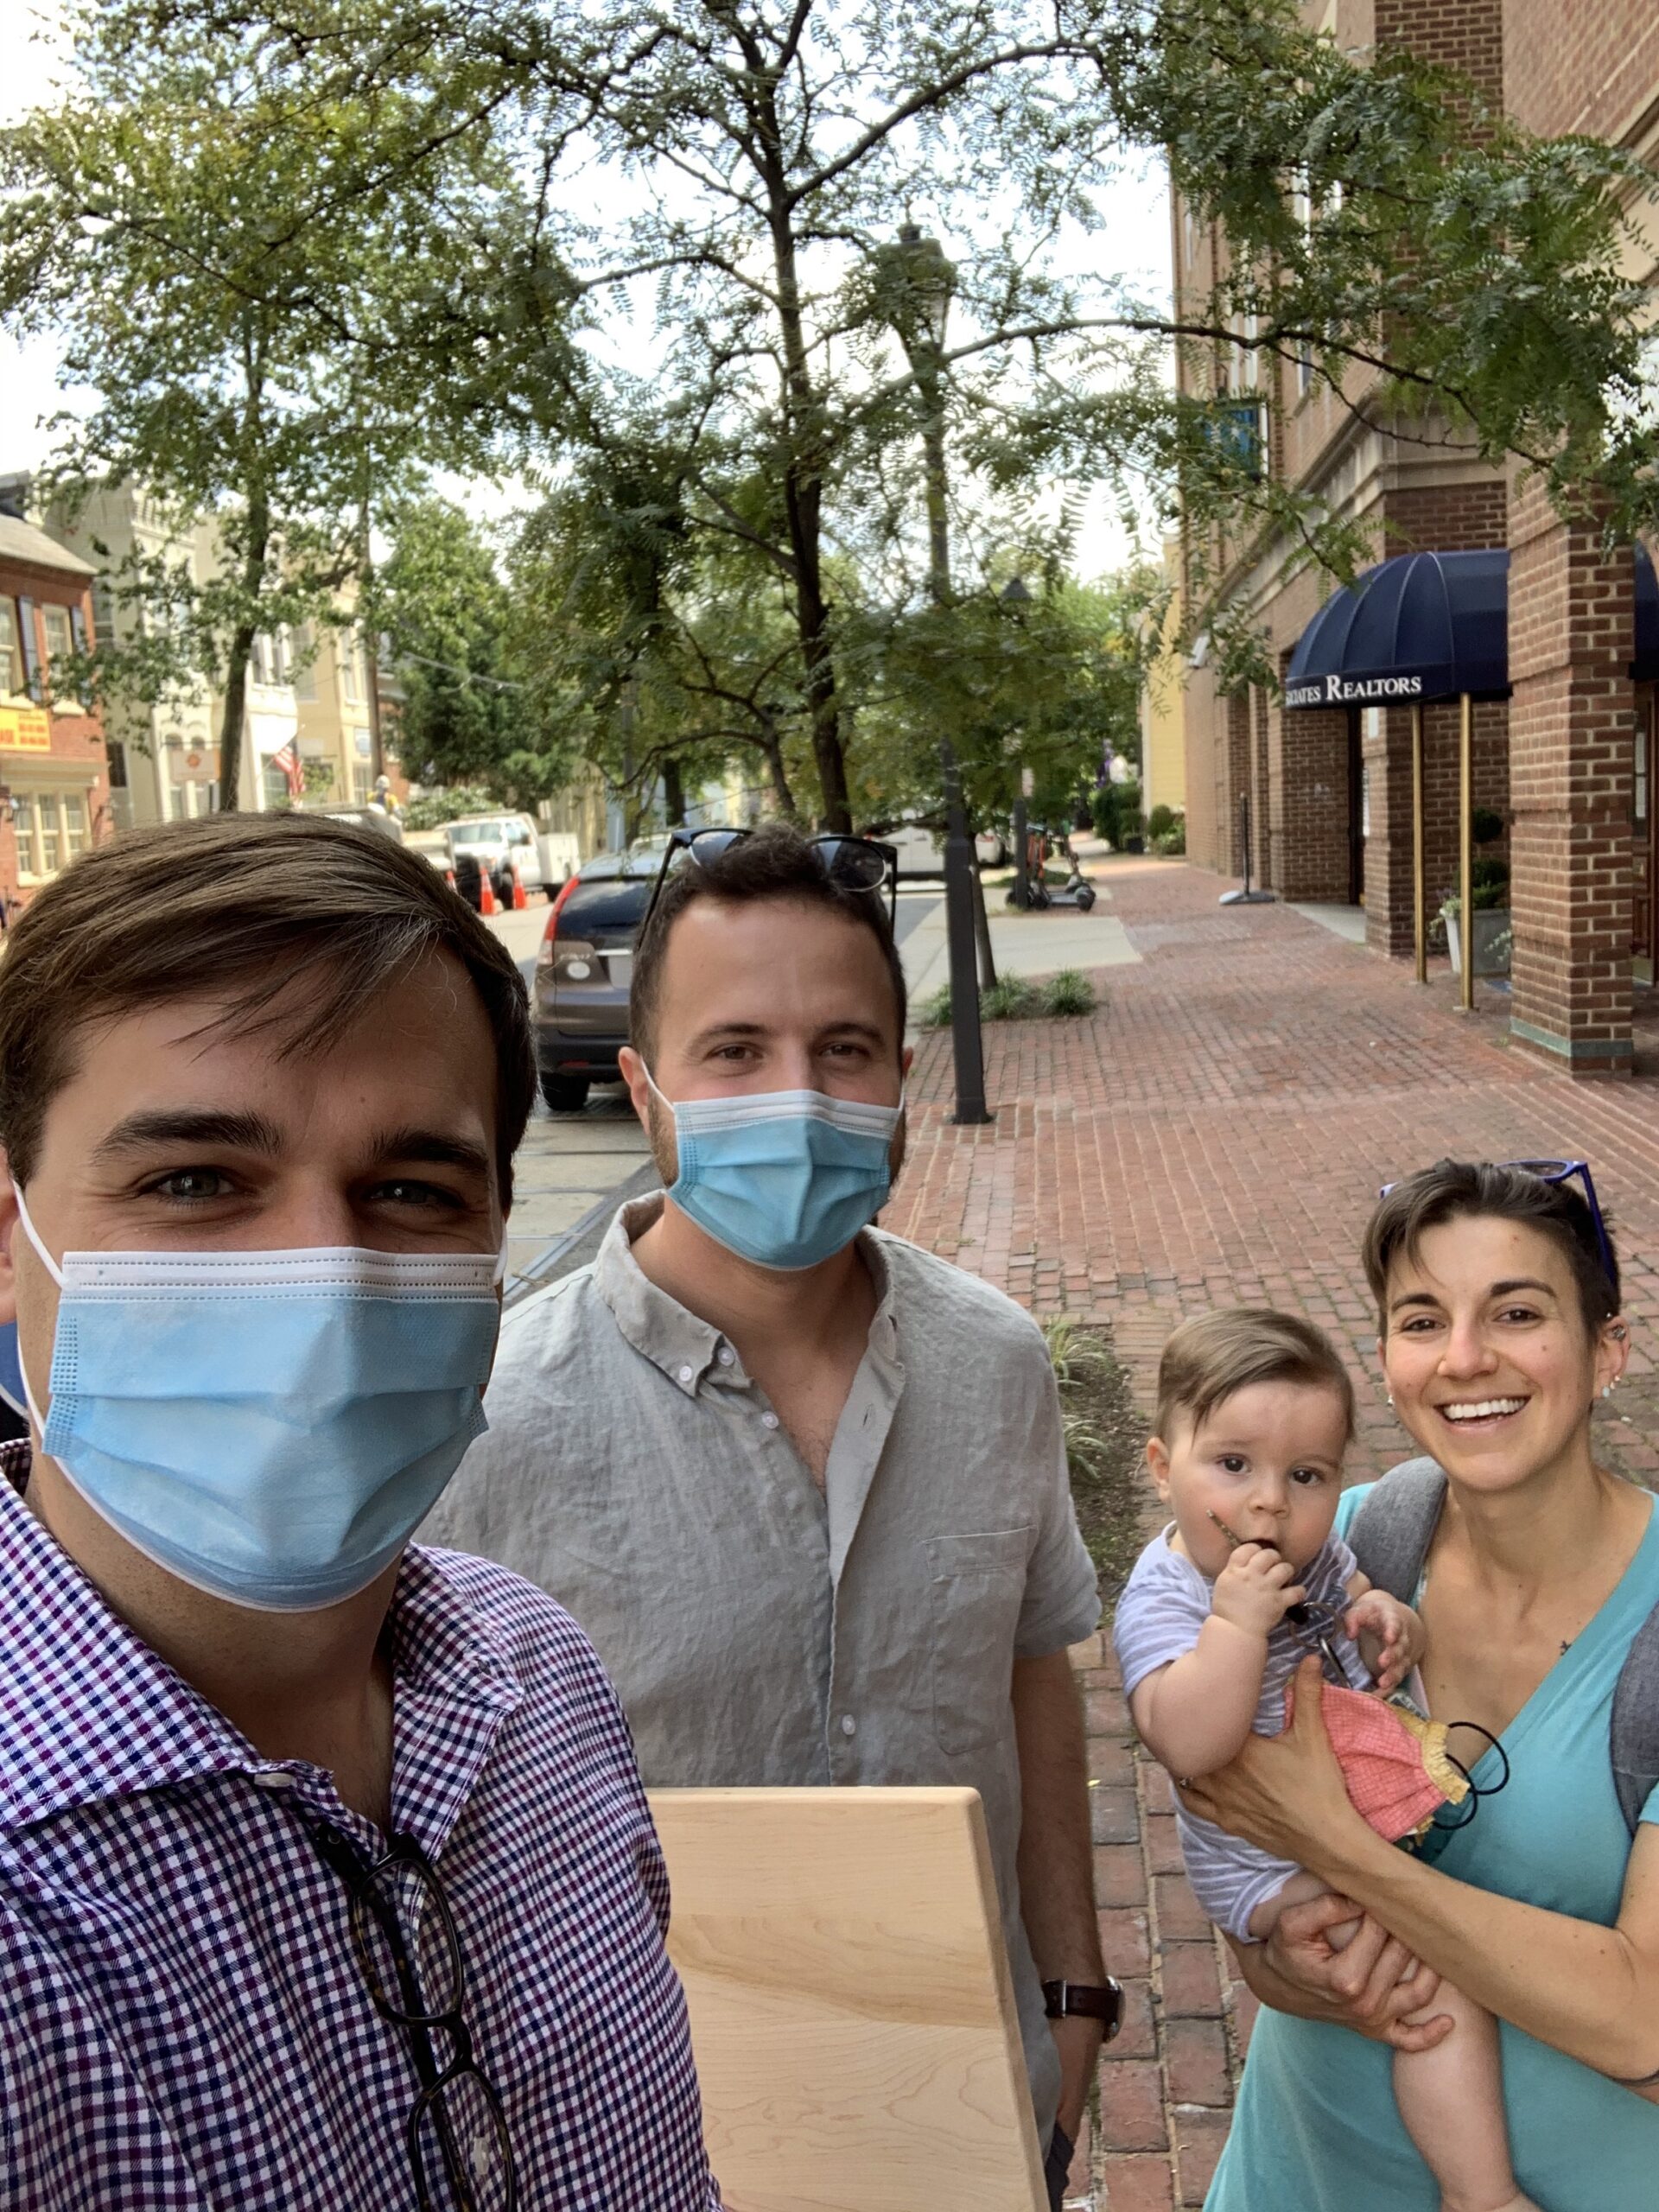
Steve is a pastor at a church in Arlington; Kelsey worked alongside him in the church while raising their two young sons. When they came to me in 2020 they had a decision every ministry family recognizes: smaller and closer to the church, or bigger and farther. We toured condos and small townhouses inside the Beltway in Arlington, Falls Church, and Alexandria. They hesitated on a townhouse that was affordable but felt like more than they should want. I told them what I believed: a home is an investment in the family’s future, not an indulgence, and they should not apologize for wanting room to grow. We widened the search just outside the Beltway and they bought a Kingstowne townhome in Alexandria with space for the boys. They now have three children and are still there.
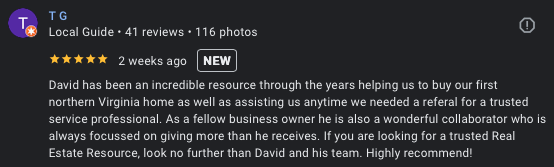
Tyler G., a Christian entrepreneur, bought in Centreville and wrote in his review that our shared faith shaped how the purchase was handled. Kay and Chuck D., a Christian couple, sold their Ashburn Village home with me in 2022 before moving to Missouri. More stories are on my Christian real estate agent page.
Ministry family looking for room to grow? Text me.
571-946-8418. I will reply myself, usually the same day.
Frequently asked questions for pastors and church staff
Can a pastor use the housing allowance to qualify for a mortgage?
Yes. Fannie Mae treats the housing or parsonage allowance as qualifying income with a 12-month history and verification from the church, and adds the full amount to monthly income. Most lenders also gross it up because it is nontaxable for income tax.
What documents does the lender need from my church?
A completed Request for Verification of Employment (Form 1005) or your most recent pay stub and W-2, plus the board resolution designating the housing allowance. A 12-month history of receiving it is required.
Does the housing allowance have to continue for three years to count?
No. Fannie Mae does not require the lender to verify continuance unless there is reason to believe it will stop.
Can my church help with the down payment?
Often, as a gift or a loan. Each has different tax and lending treatment, and the church’s own counsel should be involved. A documented gift from a church is acceptable to most lenders with a gift letter.
Is the housing allowance taxed?
It is excluded from federal income tax up to the lesser of the designated amount, actual housing expenses, or fair rental value plus utilities, but it is subject to self-employment tax. You still deduct mortgage interest and property taxes.
Where do pastors in Northern Virginia usually buy?
Inside the congregation’s footprint but outside its priciest streets: Kingstowne and Franconia, Burke and Fairfax Station, Centreville and Chantilly, Ashburn and Leesburg, Woodbridge and Bristow, depending on the church.
Have you helped pastors and church staff buy homes?
Yes. A pastor and his wife bought their first home, a Kingstowne townhome, with me in 2020 and are still there with three children, and I have worked with church families across Northern Virginia since.
Still have questions? Call or text me at 571-946-8418.
Or leave your name and number in the form just below and I will text you back.
I read every message myself and reply by call or text.
David Mount, REALTOR, CPRES, MRP
The Redux Group of eXp Realty
NVAR Platinum Top Producer